
August 24, 2026
Retirement Plan Success Demands a New Playbook
Three Practical Ways to Improve Plan Success and Retirement Outcomes


In the previous article, we explored why having a workplace retirement plan does not necessarily mean the plan is achieving its full potential.
A plan may have strong participation, competitive investments and significant assets, yet employees may still struggle to understand whether they are on track for retirement or what actions they can take to improve their outlook.
Improving retirement readiness does not necessarily require a major plan redesign or higher employer contributions. Here are three practical areas for plan sponsors to consider.
1. Make Financial Decisions Easier with Smart Design Enhancements
Many organizations view participation rates as a key measure of success. While participation matters, enrollment alone does not equal retirement readiness.
Leading retirement programs focus not only on whether employees participate, but whether they are saving enough to meet their retirement goals.
Plan design features such as automatic enrollment and automatic contribution escalation can help employees build healthier savings habits with minimal effort. These features leverage behavioural insights to encourage better long-term outcomes without requiring employees to continually revisit their savings decisions.
For example, many members join a plan and never adjust their contribution rate. Automatic escalation can gradually increase contributions over time, helping employees improve their retirement readiness without creating a significant financial burden. Even small increases, such as an additional 0.5% annually, can have a meaningful impact over the course of a career.
The principle is simple: Make positive financial decisions easier to make.
Plan sponsors should look beyond participation rates and consider whether the design of the plan encourages the behaviours that support stronger retirement outcomes. Sometimes a relatively small design enhancement can have a meaningful effect over the long term.
2. Make Communication Personal and Relevant
Retirement communication often takes a one-size-fits-all approach. But employees at different stages of their careers have different financial priorities and different retirement needs.
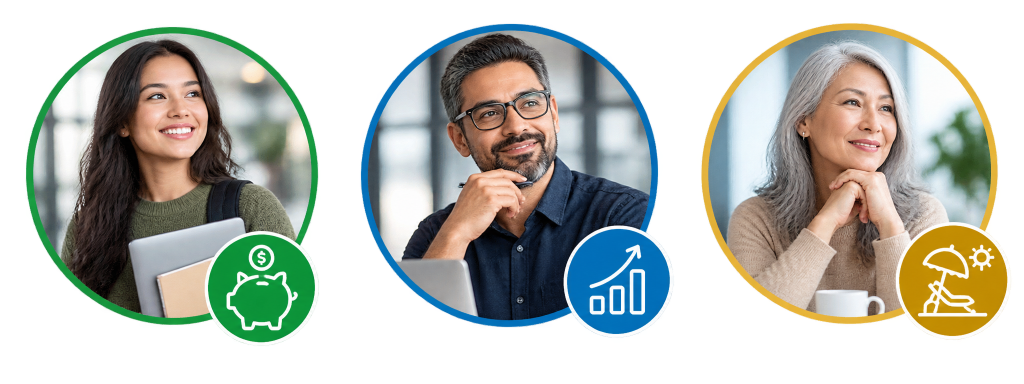
A new employee may need encouragement to start saving early and understand the value of employer contributions.
A mid-career employee may need help understanding contribution levels, investment choices and if their current savings are sufficient.
An employee approaching retirement may be more focused on retirement timing, income needs and how accumulated savings can support them once employment ends.
Communication should reflect those differences.
Rather than simply providing more information, plan sponsors can segment communications around the needs of different employee groups and focus each interaction on practical actions.
The objective is not more communication but rather to provide relevant communication that leads to action. This can make the retirement program easier to understand and more meaningful to employees, while helping sponsors focus their efforts where they are most likely to have an impact.
3. Use Data to Target Support Where It Is Needed Most
Most plan sponsors have access to more participant data than ever before. The challenge is to use that information to drive meaningful action.
For example, a plan may have strong overall participation while certain employee groups contribute at relatively low levels. Another plan may have employees approaching retirement who have accumulated meaningful savings but have limited understanding of how those savings could translate into retirement income.
These situations require different responses.
Retirement readiness analysis can help sponsors identify trends across their workforce and focus on education, communication and plan initiatives where they are most needed. Instead of applying the same strategy to everyone, data can help sponsors identify specific groups that may benefit from additional support.
This is particularly valuable because retirement readiness is not simply a plan-level outcome. It can vary significantly across different employee populations.
Turning Insights into Action
The first step is evaluating your retirement program through a member-centric lens. Key areas to review include:
• Plan design and contribution structures
• Employee engagement and communication strategies
• Investment menus and default options
• Retirement readiness metrics and projections
• Pre-retirement education and income planning resources
• Plan governance, compliance, and industry best practices
A plan evaluation only creates value when it leads to better decisions and action.
For example, a useful retirement readiness analysis should therefore move beyond reporting statistics. It should help identify where potential gaps exist, determine appropriate actions and provide a way to measure whether those actions are making a difference. This creates a more disciplined approach to improving the retirement program over time.
Similarly, when reviewing member behavioural data, plan sponsors often explain employee actions, or lack of action, by pointing to unknown personal circumstances. While individual motivations may never be fully understood, a sponsor's responsibility is not to determine why members behave in a certain way. Rather, it is to create an environment that enables and encourages informed decision-making.
Small Changes Can Lead to Meaningful Results
Improving retirement readiness does not always require a complete overhaul of the retirement program. In some cases, the most effective improvements may be relatively targeted:
• Increasing participation among a specific employee group
• Encouraging higher contribution rates
• Improving the relevance of member communications
• Simplifying investment decisions
• Providing additional support to employees approaching retirement
• Using plan data more effectively to identify areas of concern
Meaningful improvement often comes from helping employees make better decisions, taking advantage of available plan features, and understanding the actions needed to improve their long-term financial outcomes.
The most successful retirement plans are those that translate design into results. Their effectiveness is not determined by the complexity of their features, but by their ability to help employees achieve greater retirement readiness. Ultimately, plan success is measured by outcomes, not offerings, and by the futures employees are empowered to build.
The Value of an Independent Perspective
It can be difficult for an organization to objectively evaluate its own retirement program.
An independent review can help bring structure and perspective to the process, identifying strengths, gaps and opportunities without assuming that a complete redesign is necessary.
At Joseph Partners, we take a member-centric and organization-focused approach to retirement plan consulting. We help plan sponsors assess their retirement programs, understand member behaviour and retirement readiness, and identify practical opportunities to improve the plan's effectiveness. Our work can include plan assessments, retirement readiness analytics, member communication strategies, investment and default option reviews, plan design analysis, and governance and compliance reviews.
Contact us at hello@josephpartners.com to connect to our Retirement Specialist.
